

Credit Card : Wallet & NFC
4.6

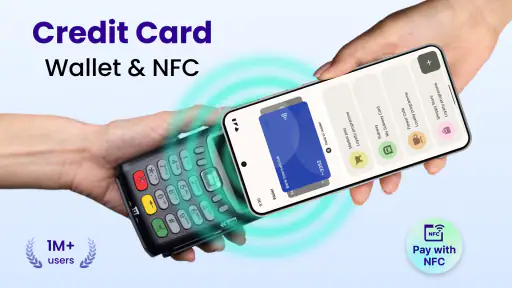
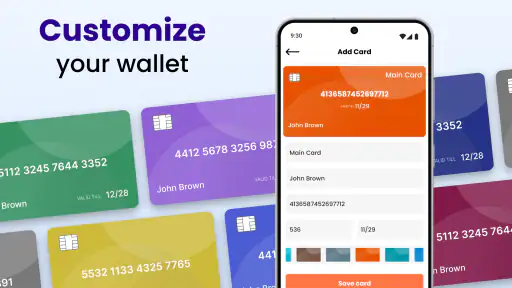
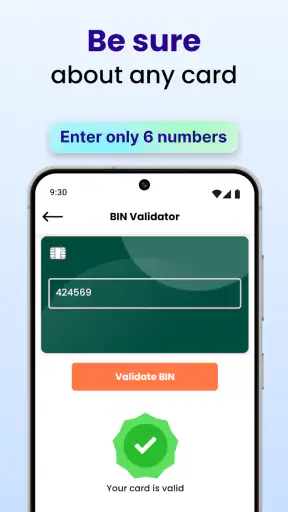
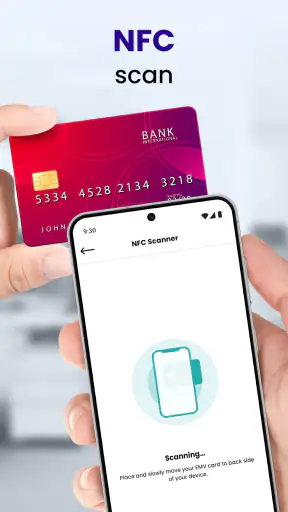
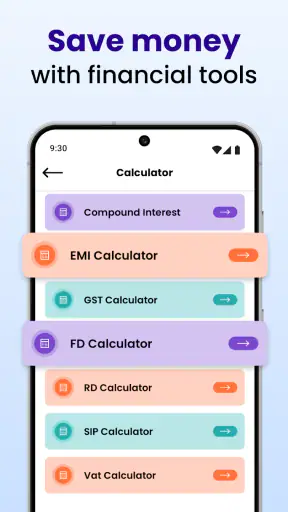
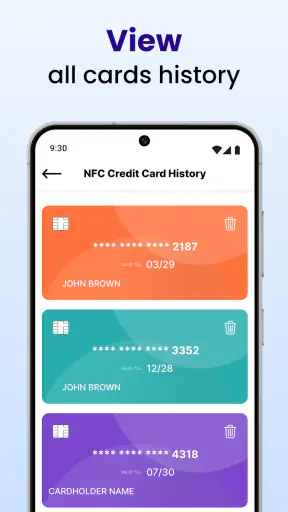
Credit Card : Wallet & NFC is the kind of finance app that looks simple until you try to use it for a specific task. I approached it as a practical tool for checking card details, working with NFC scanning, and validating a card’s BIN information rather than as a complete replacement for a bank’s official mobile wallet. That distinction matters, because the app’s usefulness depends heavily on what you need to do and on whether your phone can communicate with the card.
In my experience, its appeal is clear: it brings card-related utilities into one place, costs nothing to install, and is aimed at ordinary users rather than finance professionals. The developer, Galaxy studio apps, has positioned it in the finance category, while the store’s short description simply calls it “Credit Card.” The longer summary gives a better idea of its purpose by focusing on a mobile wallet, an NFC scanner, and a credit or debit card BIN validator.
Where the first-use experience can become confusing
The first point to understand is that a BIN validator does not work like a card payment terminal. A BIN, or Bank Identification Number, is the opening part of a card number used to identify information associated with the issuing network or institution. Checking that information can be useful when organizing cards or investigating an unfamiliar card, but it does not prove that the card is active, funded, safe, or approved for a transaction.
That difference is easy to miss when an app combines wallet language with card validation. I would not treat a successful lookup as a guarantee that a purchase will go through. I would also avoid entering a full card number unless the app’s current screen clearly explains why it is needed. For routine identification, the relevant opening digits are usually the important part, while the complete number and security code should remain private.
NFC scanning creates another common point of friction. The phone must have NFC hardware, the feature must be switched on, and the card or tag must be positioned close enough to the phone’s NFC area. The exact location varies from one handset to another, so moving the card slowly across the upper back, center, and lower back of the phone is more useful than pressing harder or tapping repeatedly.
Some users may expect the app to read every payment card in the same way. That is not a safe assumption. Cards differ in how they expose information, and a phone may detect an NFC signal without presenting useful details to an app. A failed scan therefore does not automatically mean the card is damaged or that the application is broken.
The app has attracted a 4.6 average from around 68 thousand ratings, and it has passed the five-million-install mark. Those figures suggest that the basic idea is understandable to a broad audience, but they should not be read as a promise that every handset and every card will behave identically. NFC compatibility is particularly dependent on the hardware and the card itself.
What I would prepare before opening the scanner
Before troubleshooting inside the app, I would check the phone’s own NFC setting. On Android, the location of that control depends on the manufacturer and software layout, so the quickest approach is usually to search the device settings for “NFC.” If the option does not appear at all, the phone may not support NFC, and changing settings inside the app will not solve that limitation.
I would also remove thick cases, magnetic accessories, and card holders during testing. They can place extra material between the phone and the card, making an already sensitive connection less reliable. This is especially relevant when a user assumes that a brief vibration or sound means the entire scan has completed. Detection and readable data are not necessarily the same thing.
Keeping the card still is often better than waving it around. I place it flat against the back of the phone, try one likely NFC position, and hold it there for a moment. If nothing happens, I move it to another part of the phone and repeat the test once. Rapidly changing positions can make it difficult to tell whether the problem is distance, alignment, or the card.
The operating system also matters. Credit Card : Wallet & NFC supports Android 7.0 and later, which covers a wide range of devices, but an eligible Android version does not guarantee that the handset includes NFC or that its NFC implementation will interact with a particular card. I would therefore check the physical phone specifications before relying on the scanner for an important task.
A safer way to use the BIN validator
For the BIN tool, I would begin with a card that I already understand and use the result as an informational cross-check. I would compare the displayed network or issuer-related information with the card’s own details, but I would not use the result to decide whether a seller, message, or online request is trustworthy. A BIN can identify a broad card range; it cannot authenticate the person holding the card.
There is also a practical privacy habit worth adopting: avoid screenshots that expose the full card number, and do not share lookup results containing more information than someone needs. If the app allows a result to be viewed without retaining unnecessary card details, that is the approach I would choose. The safest workflow is to enter as little sensitive information as the task genuinely requires.
This makes the validator more useful for sorting personal cards, checking whether a number appears to belong to the expected card network, or understanding a card received from a legitimate source. It is less suitable as a fraud-detection system. Anyone trying to verify a suspicious payment should contact the bank through its official channel instead of relying on a third-party lookup.
Recovering a workflow when something goes wrong
When a scan fails, I would avoid immediately uninstalling the app or repeatedly entering card information. First, I would close the scanner, confirm NFC is enabled, remove the case, and try the card in a different position. Testing with another known NFC-capable card or tag can help separate a phone problem from a card-specific problem, provided that the second item is safe to use for testing.
If another item is detected but the original card is not, the issue may be related to the card’s NFC behavior rather than the application. If nothing is detected, I would test the phone’s NFC with a known compatible item and check whether another application on the device can recognize it. This is a useful recovery sequence because it avoids guessing and narrows the cause one step at a time.
Restarting the phone is a basic step, but it can be worthwhile after changing NFC settings or installing an update. I would also make sure the app is running its current version, which is 3.0.5, rather than assuming the installed copy is up to date. Version information is available in the app’s store entry, and updating can be sensible when a problem appears after a system change.
For a BIN lookup that returns an unexpected result, I would first check the digits carefully. A single mistyped number can produce a result that looks convincing but belongs to another range. I would then compare the result with the physical card and, if the discrepancy affects a real financial decision, confirm it with the issuing bank. The app should be treated as a convenience tool, not the final authority.
One non-obvious trade-off is that combining several card utilities can save time while also encouraging overconfidence. A user may see a neat result and assume the underlying card has been fully checked. I think the best workflow is to use the app for organization and preliminary information, then move to the bank’s official app or support channel for account status, transactions, card freezes, and identity-sensitive actions.
When the app is not the cause
Many apparent app failures are actually caused by the card, phone, or surrounding conditions. A metal wallet, a case with a card compartment, or a phone placed near another contactless card can interfere with a scan. Even the position of the NFC antenna can be surprising, particularly on larger handsets. Trying a bare phone and a flat card is a better test than changing several variables at once.
Bank cards also differ in their contactless behavior. Some may be designed primarily for tap-to-pay terminals, while others may not expose information that a general NFC utility can read. A payment terminal and a phone application do not necessarily use the same process, so a card that works perfectly at a shop can still provide little or no useful information in a scanner.
There is a similar distinction between this app and a bank wallet. A bank’s official application is normally the better choice for viewing balances, checking transactions, managing a card, reporting fraud, or requesting a replacement. A platform wallet may be preferable when the main goal is everyday contactless payment and the device already supports that service. Credit Card : Wallet & NFC makes more sense when you specifically want a card utility and a BIN-oriented check in a lightweight application.
I would also be cautious about treating the word “wallet” as proof that the app replaces a physical wallet. The practical value here is centered on card information and NFC-related interaction. It should not become the only place where important financial details are stored or checked. Keeping official banking access available gives you a reliable fallback when a scan or lookup does not behave as expected.
Another limitation is the presence of in-app purchases, which range from $0.99 to $99.99 per item. The app is free to install, but anyone who dislikes optional paid elements should review each screen carefully before confirming a purchase. I would not assume that every utility is included in the free experience, and I would involve the device owner’s normal purchase controls when sharing a phone with family members.
Who will get the most from it
I see the strongest fit for someone who handles several cards and wants a quick way to inspect card-related information without opening a full banking application. It can also suit a curious Android user who wants to test NFC behavior, provided the phone supports NFC and the user understands that scanning results depend on the card.
A realistic everyday example would be sorting personal cards after replacing an old one. I could use the BIN validator to check whether the opening digits correspond to the expected card range, label the card correctly in my own records, and then use the NFC scanner as a separate experiment rather than as proof that the card is ready for payment. If the scan fails, I would still be able to use the bank’s official tools for the information that actually matters.
The app is less appropriate for someone who wants a complete banking dashboard, a guaranteed contactless payment solution, or a professional card-verification service. It is also not the right choice for making decisions about suspicious cards based only on a BIN result. In those situations, the bank, card network, or official payment provider is the safer and more capable alternative.
Age suitability is listed as Everyone, which matches the straightforward utility concept, but younger users should still learn not to share card numbers or security codes. The age label does not remove the need for sensible financial privacy. I would explain that distinction to anyone using the app for the first time, especially if the phone is shared.
My practical verdict
After looking at the app through the lens of setup and recovery, I think Credit Card : Wallet & NFC is best understood as a focused companion for card inspection, not a universal financial wallet. Its free entry point, accessible Android requirement, and combination of NFC and BIN tools make it convenient for quick checks. The 5M+ install count and strong average rating also show that the concept has found a sizable audience.
Its weaknesses are mostly about expectations. NFC is dependent on hardware, positioning, card design, and interference from accessories. BIN results are informative but limited. A wallet-style interface can make the app feel more authoritative than it really is, so I would keep official banking tools involved whenever money, identity, or fraud is at stake.
My recommendation is therefore conditional but positive. If you want a free finance utility for experimenting with NFC and checking card-number ranges, it is worth trying. Start with a non-sensitive test, use only the information necessary for the task, and follow the simple hardware checks before blaming the app. If your priority is payments, account management, or strong financial security controls, I would choose the bank’s official app or a trusted platform wallet instead.
In short, the application earns its place through convenience rather than depth. Used with realistic expectations, it can save a few steps and help organize basic card information. Used as a substitute for a bank, a payment terminal, or a fraud service, it will inevitably disappoint. My main advice is to treat the scanner and validator as practical helpers, while keeping final financial decisions in official channels.
For readers deciding whether to install it, the key details are simple: it is a free finance app from Galaxy studio apps, rated for Everyone, with optional in-app purchases and a current version of 3.0.5. I would install it for targeted card-related tasks, test it patiently on compatible hardware, and remove it from the workflow whenever the task requires account-level authority rather than general card information.
4.6
493.00 Reviews
Pros
- Supports contactless NFC payments on compatible Android devices.
- Keeps card details organized in one convenient digital wallet.
- Can reduce the need to carry multiple physical cards.
- Quick access to payment information when shopping.
- Useful for checking and managing cards while traveling.
Cons
- NFC features depend on device hardware and regional availability.
- Some banks or cards may not be supported by the app.
- A lost or unprotected phone could expose sensitive payment data.
- Requires a compatible operating system and regular app updates.
- Payment acceptance varies between merchants and card terminals.


